Follow the path
See expected rates after each published decision, with a clear distinction between the move at a meeting and the cumulative change.
See the Canadian and US interest-rate paths priced into futures, and how those expectations are changing.
Switch between the Bank of Canada and Federal Reserve to explore expected policy rates, the move priced at each meeting, and the cumulative change from the policy reference.
Compare the latest available pricing with earlier observations, inspect meeting outcomes, and download the meeting table for your treasury discussions. Pricing dates and conventions stay visible alongside the figures.
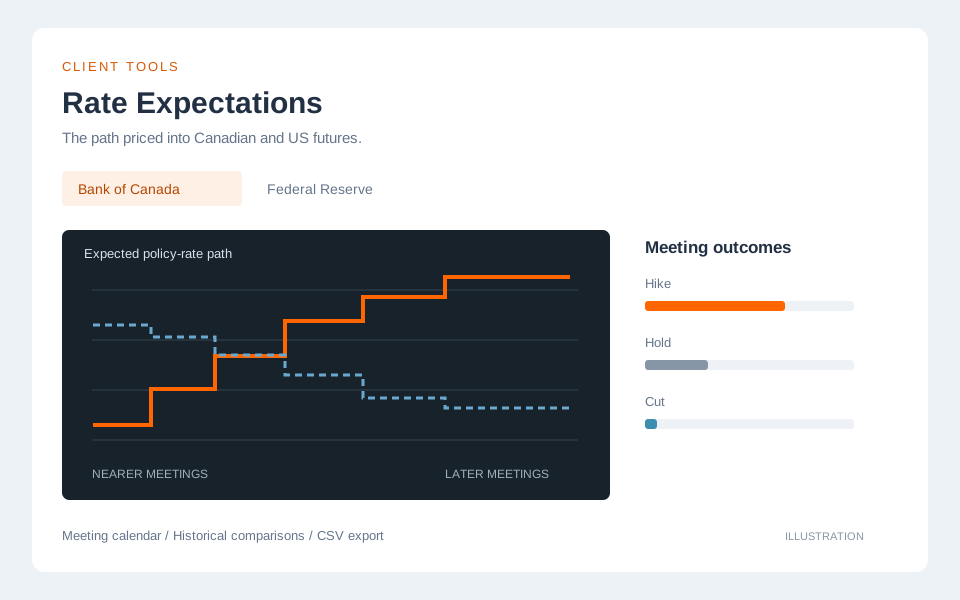
Illustrative view. Open the client tool for dated market observations.
See expected rates after each published decision, with a clear distinction between the move at a meeting and the cumulative change.
Review Canadian hike, hold and cut equivalents, and the modelled distribution of US target ranges after each meeting.
Overlay earlier rate paths and compare historical meeting pricing. Export the current table as a CSV for further analysis.
Futures price average overnight rates. Estimating individual meeting outcomes requires assumptions, especially for later Canadian meetings inferred from quarterly contracts. The dashboard identifies indicative estimates, distinguishes closing prices from delayed quotes, and keeps unsupported meetings visible as unavailable.
Market-implied expectations include risk premiums and may change quickly. They are useful context for financing, cash-flow and currency discussions, rather than a prediction of central bank decisions.